An adjuster arrives, walks a roof for forty minutes, and leaves with a handful of photographs and a note. A week later the owner receives a scope that covers a fraction of what the roofer found. That gap, between what is on the roof and what ends up on the claim, is where documentation matters. In West Jordan, UT, roof claim assistance means producing a record so clear and so tied to specific roof sections that the person reading it can follow the damage from cause to cost.
We are the roofer, not the insurer and not the adjuster. Coverage decisions belong to the carrier. What we supply is the evidence of what happened to the roof, the repair scope that follows from it and a willingness to stand on the roof with the adjuster and point at what we found.
What the evidence file holds
A good claim file starts on the day damage is found. It holds dated photographs of each affected roof section from fixed points, close-ups of the damage itself, a sketch of the roof with each photo location marked, and a list of the temporary measures taken to stop water. Where moisture is suspected, it adds an infrared moisture survey map and the core cut results that confirm it.
The file also records what is not damaged. A roof section that was checked and found sound is listed as such, because an adjuster who sees only the damaged areas has no way to judge their share of the roof. Separating storm damage from age, wear and prior leaks is a point where careful records help the owner more than broad claims do. The same photographs and moisture readings feed a written roof condition report, so the owner holds one document that answers both the carrier's questions and a lender's or buyer's.
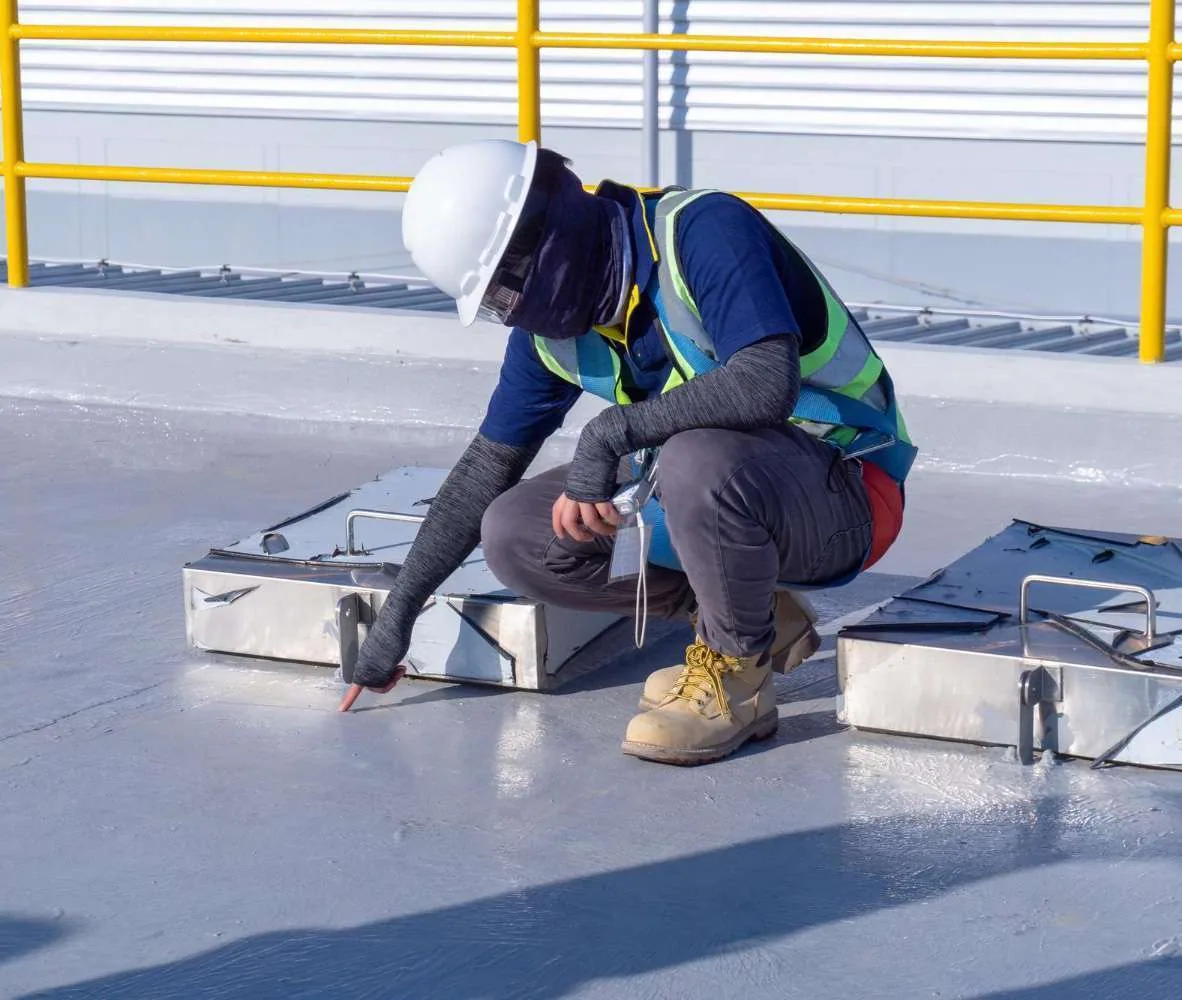
Photographs are taken in a fixed order so they can be matched to the sketch: overview of the section, the edges, the seams, each curb and penetration, and then the damaged area at arm's length and close up with a scale reference. Each image carries a date and a section label. A file built this way lets someone who has never seen the roof follow it from the first picture to the last.
Cause and timing: telling the story straight
Insurers ask what happened and when. The record answers with what the roof shows: the direction of wind damage across edge metal, the pattern of impact marks, the ice that backed water under flashing, the date a stain appeared. We separate what we can state from the roof itself from what the owner reports. A stain seen on a ceiling in March tells us water entered before March, and the walk identifies where; it does not by itself tell us on which day a storm occurred.
For a snow or ice event, the airport normals for Salt Lake City record winter snowfall and freezing periods valley-wide. Because that is not a reading of any one roof, we lean on the building's own evidence and on any dated weather report the owner or adjuster hands us. The more specific the dates, the cleaner the claim reads.
Writing the repair scope
The repair scope is the document adjusters compare with their own estimate, so it lists quantities. Square footage by roof section, linear feet of flashing and edge metal, count of penetrations, thickness and type of insulation affected, and the labor for each step. Where the roof's current condition affects the repair, such as a section with wet insulation that must come off, the scope says why and shows the moisture reading behind it.
Code can alter the scope. Utah put the 2024 IBC and the 2024 IECC into effect on July 1, 2026, each with state and local amendments. A repair large enough to trigger current requirements for insulation or attachment may include costs beyond the damaged material, and we mark those lines separately so everyone can see which belong to the damage and which to the code. The storm damage repair scope and the claim scope should match, line for line.
The adjuster walk
When the carrier sends an adjuster, we ask to be on the roof at the same time. The visit goes faster when someone who has already walked the roof can point out the lifted edge, the soft area and the line of impact marks, with the photographs on a tablet. The adjuster sees what the record shows and can compare it with their own findings on the spot.
If the adjuster and the record disagree, we ask which condition they read differently and look at it together. A disagreement about whether a seam failure is age-related or storm-related can sometimes be resolved with a closer photograph or a cut sample. When it cannot be, the record shows both views and the owner decides how to proceed. We do not argue coverage. We argue only about what the roof shows.
Repairs while the claim is open
Water continues to enter a damaged roof while a claim is processed, so temporary protection goes on immediately and its cost is recorded. Permanent repairs usually wait for the adjuster's visit, and the owner is told clearly what can be fixed now without disturbing evidence. An emergency repair can be completed in a way that preserves the damaged material for inspection.
When the carrier's decision comes, we compare it with the written scope and explain the differences in roofing terms, line by line. If a section was excluded or reduced, the owner can ask for a review with the evidence file in hand. The decision stays the carrier's.
Some claims run for weeks, and conditions on the roof change in that time. Another melt, another wind event or simply foot traffic can alter what the roof shows. For that reason we re-photograph the temporary measures at intervals, record any new water entry with its date, and keep each addition in the same file. If a second event occurs while the first claim is open, the file separates the two so each is read on its own evidence.
Who uses this in West Jordan
Owners, managers and tenants of the commercial, service, office and mixed-use buildings in the city's general plan can all end up filing a roof claim. Multi-building owners get one reporting format, which helps when several roofs are affected by the same event, and insurance restoration professionals can use the same photograph and scope format. The same record format works for buildings in West Jordan, whether along Redwood Road and 7800 South, around the Gardner Village area or near Old Bingham Highway.
Commercial Roofing Questions
When should the roofer be called, before or after the insurer?
Call us first if water is coming in. We stop the water and photograph the damage, and then you can report the claim with the evidence in hand.
Will the claim cover the whole roof?
That is the carrier's decision. Our record shows which sections are damaged by the event and which are not, so the scope fits the evidence.
What if the adjuster calls the damage wear?
We look at the conditions together. Impact patterns, direction of wind lift and dated stains help separate event damage from age, and a cut sample can settle some cases.
Do temporary repairs hurt the claim?
No. They are expected, and the claim record lists them with before and after photographs.
What documents should the owner gather?
The policy declarations if available, past roof invoices, any warranty paperwork and the date damage was first noticed.
Start the roof record before the claim is filed
Tell us where water appears, when you first saw it and how the roof is reached. We will document the roof by section, stop the water, and explain what must be confirmed before a repair line or schedule is set.